
- Home /
- Loan Programs /
- Stated Income Home Loans
Your tax returns don't tell the whole story
Stated Income Home Loans, the Modern, Verified Version
Today’s stated-income-style programs let Arizona business owners and investors qualify with a CPA-prepared P&L, bank statements, or assets. Reduced paperwork, fully underwritten loans.
Get Pre-Approved
“Stated income” earned a bad reputation before 2008, when loans were approved on a borrower’s word alone. Those loans are gone. What exists today is smarter: alternative documentation programs that verify your ability to repay through business financials, deposits, or assets, just not through tax returns that understate what your business really earns.

Bank statement loan
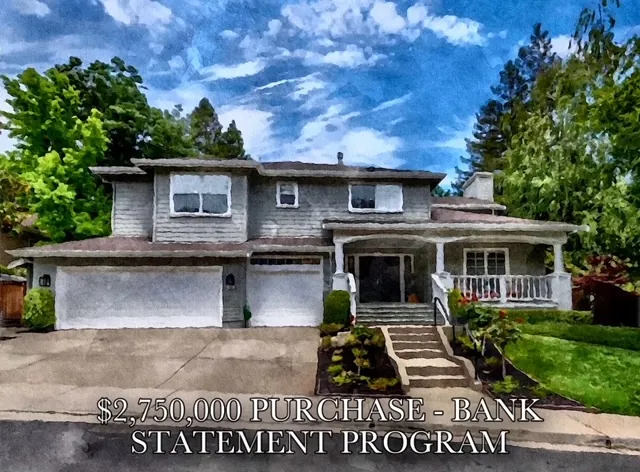
Bank statement program
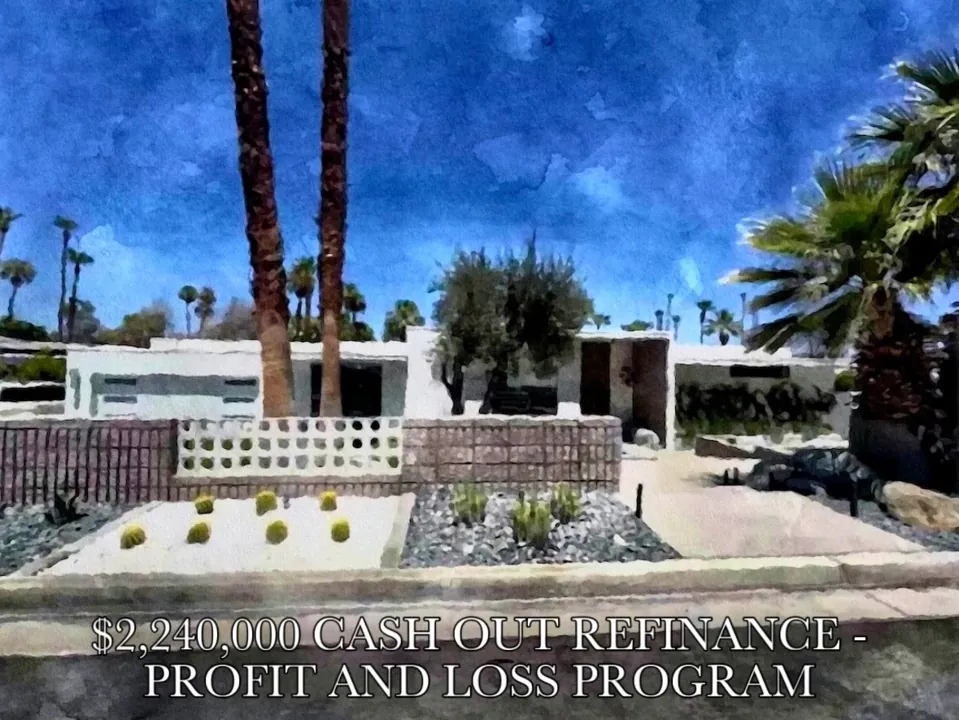
Bank statement loan

Bank statement loan

Bank statement program
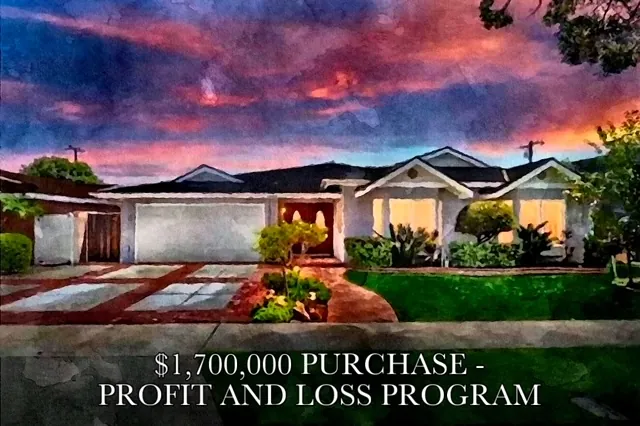
P&L loan
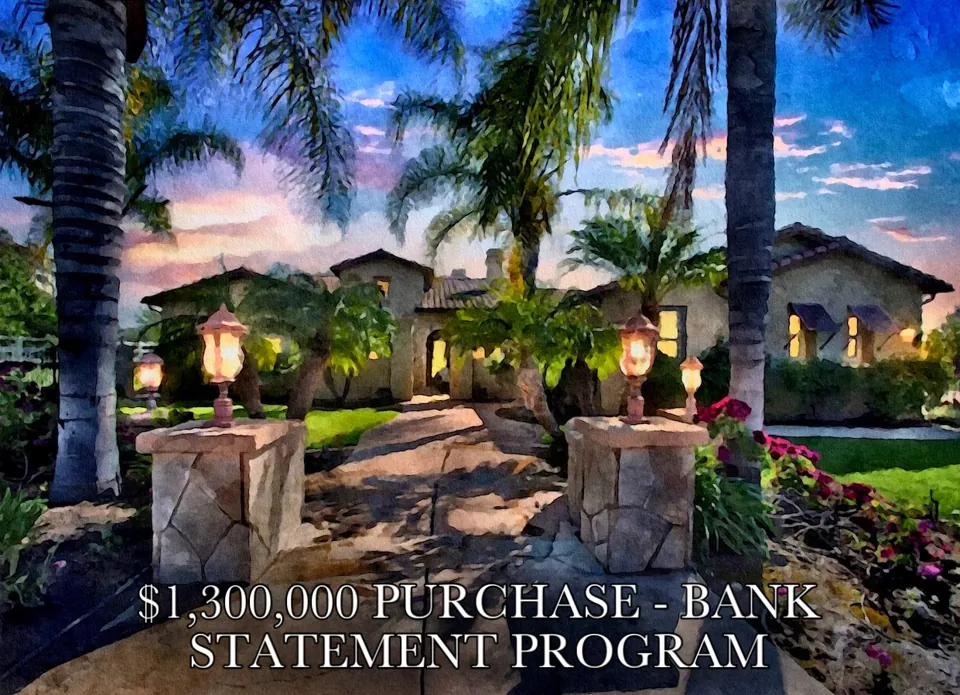
Bank statement program
Bank statement program

P&L program

Bank statement refinance
- Who this is for
Today's stated-income-style options
- P&L-only loans, qualify with a profit-and-loss statement prepared by a CPA or licensed tax preparer. Often the lightest documentation path for an established business.
- Bank statement loans, 12-24 months of deposits stand in for tax returns. Full guide →
- Asset-based qualification, your portfolio does the qualifying. Assets as income →
- DSCR investor loans, for rentals, the property’s income qualifies, and your personal income is never documented. DSCR loans →
How a P&L loan works
- our CPA or tax preparer prepares a 12-24 month profit-and-loss statement for the business.
- The lender reviews the P&L alongside credit, assets, reserves, and the property, some programs also sample a few months of statements for consistency.
- You qualify on real business performance, not the taxable remainder after depreciation and write-offs.
- Real closings
A
- $3.5M Dana Point cash-out refinance
used a P&L program to unlock roughly $1M in liquidity, and a
- $2.2M Hollywood Hills refinance
delivered over $1M cash to a self-employed homeowner. Read the case studies →
Frequently asked questions
Are stated income loans legal now?
Modern programs are fully legal non-QM loans. Lenders must verify your ability to repay, they simply do it through business financials, deposits, or assets instead of tax returns. Nothing is taken on your word alone.
What credit score and down payment do I need?
Guidelines vary by lender, but most programs look for solid credit and 10-25% down or equivalent equity, with stronger terms as the file strengthens. Paul will match your profile to the lender whose box you actually fit.
Which is better for me, P&L, bank statements, or assets?
It depends on how your income flows. Clean, consistent deposits favor bank statements; a complex entity structure with a good CPA often favors P&L; substantial portfolios favor asset-based programs. Paul routinely prices a file more than one way and shows you the comparison.
Can investors use stated income programs?
Yes, and for rental properties, a DSCR loan may be even simpler, since it qualifies on the property’s rent rather than your income at all.
Related programs
- Bank Statement Loans
Qualify with deposits instead of tax returns.
- Assets as Income
Let your portfolio carry the qualification.
- Stated Income Loans
P&L and reduced-documentation options.
- Cash-Out & Seconds
Equity strategies for high-value homes.
Talk it through with Paul
Get a straight answer about your scenario, usually in one conversation.
Paul Healey
Personal NMLS: 328365 Company: Spectrum One Mortgage Company NMLS: 332549